Seasoned vs. New Tradelines: Which Fits Your Goal?
How account age affects your credit profile, and how to decide which type actually fits what you’re trying to accomplish.
Looking to purchase verified AU tradelines? Browse our tradeline inventory with escrow-backed transactions.
Watch: Seasoned vs New Tradelines – Which Is Better?
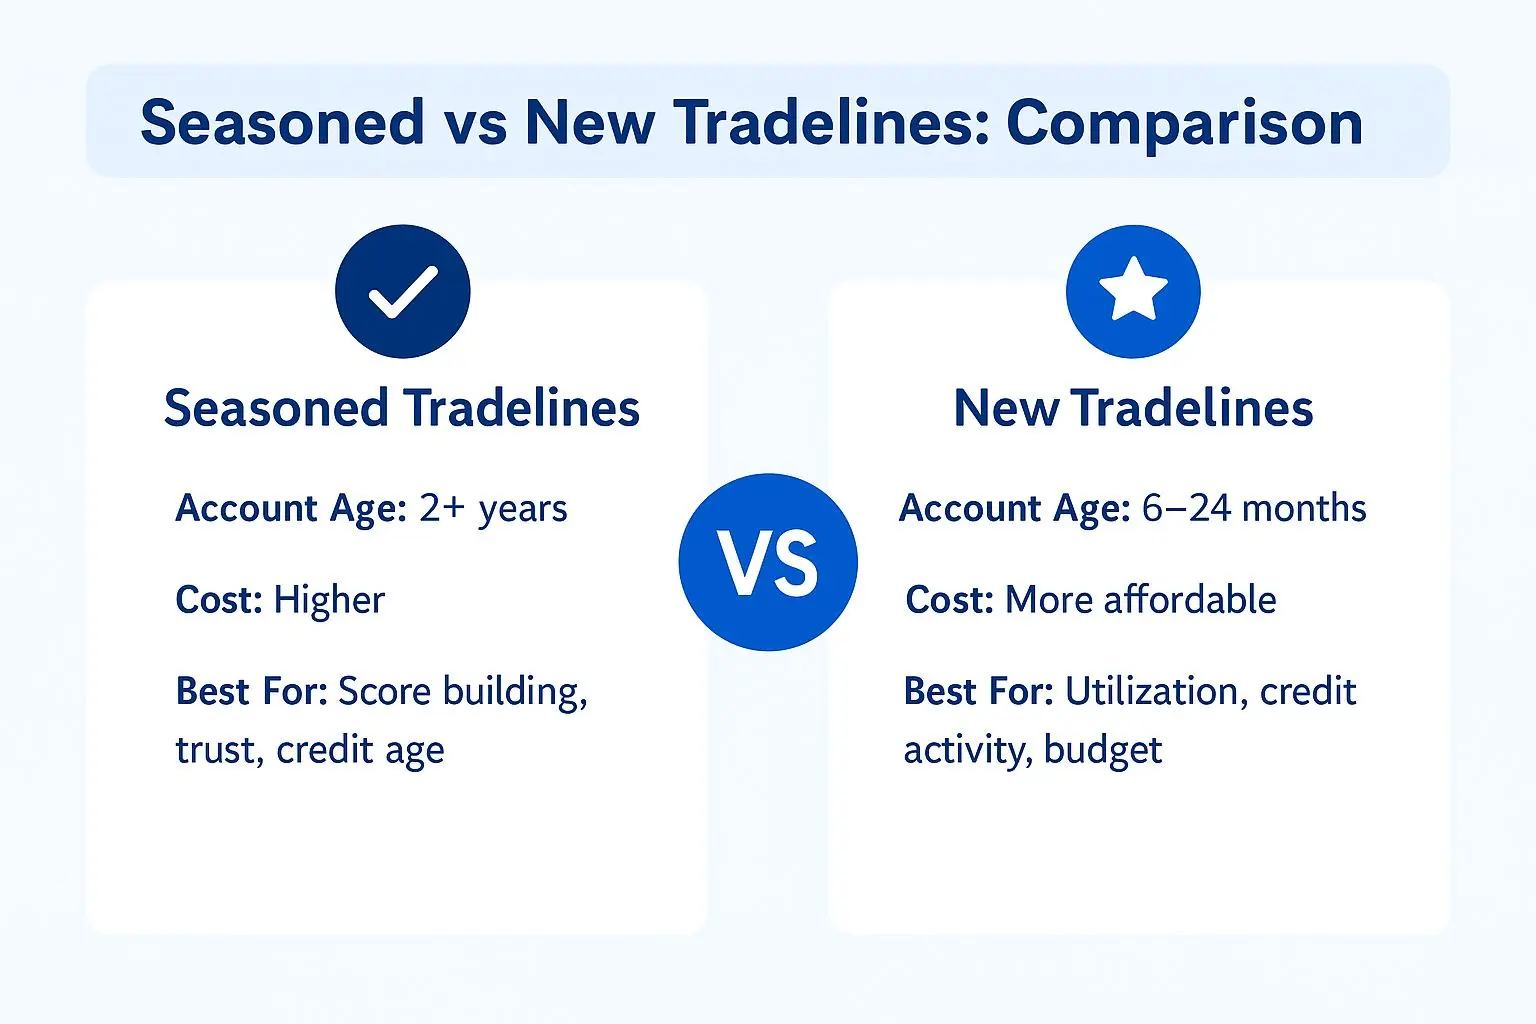
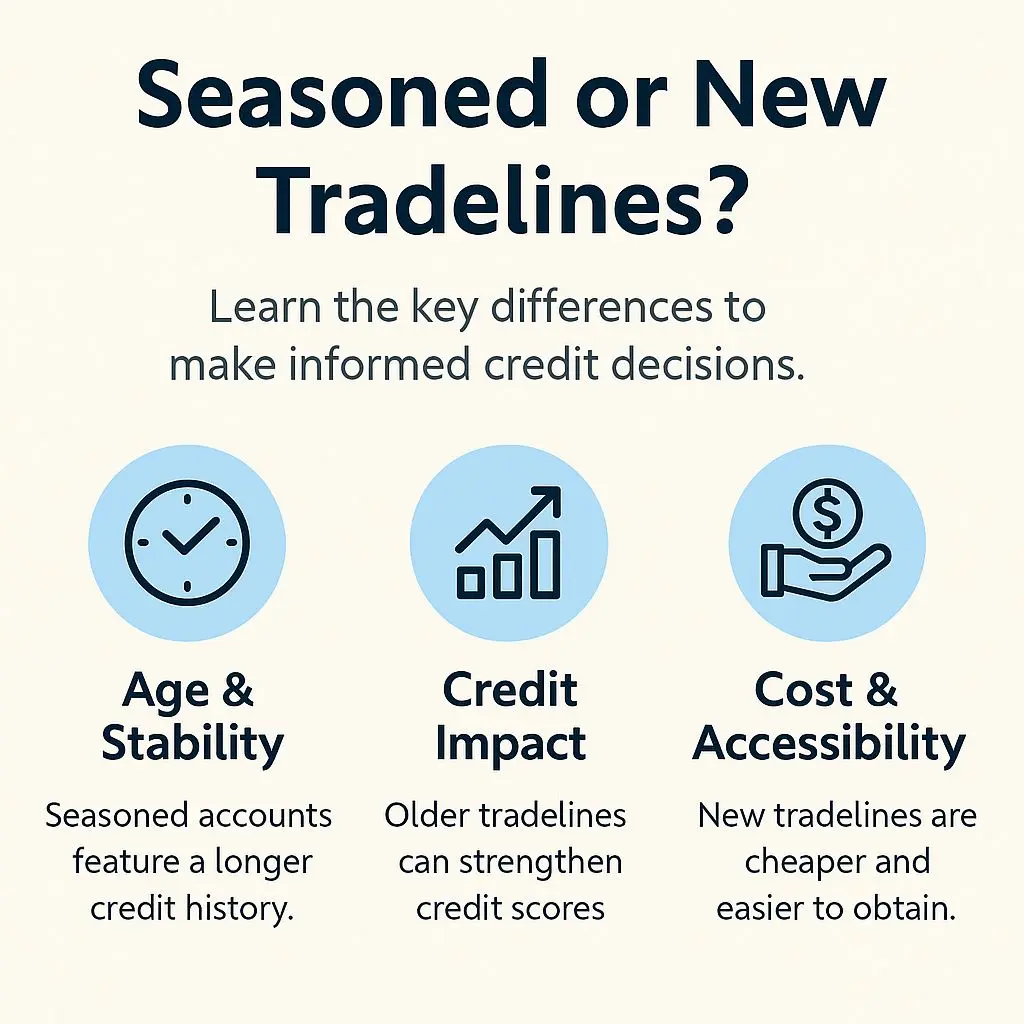
When comparing seasoned and new tradelines, the real question is what you’re trying to accomplish. Seasoned tradelines — generally two or more years old — tend to add more stability to a credit profile. Newer tradelines are more affordable and still useful for utilization or account activity, particularly when layered strategically with other accounts.
For independent context on how authorized-user accounts affect credit scoring, the Federal Reserve Board’s own research is worth reading directly: Credit Where None Is Due? Authorized User Account Status and “Piggybacking Credit”.

Reviewed by
Raquel Hudson, Tradeline Specialist
More than a decade of experience in tradeline placement, credit report analysis, and client support. Read her full background →
Why Tradeline Age Matters
The age of an authorized-user tradeline affects your credit profile mainly through one specific factor: the average age of your accounts, a known component of both FICO and VantageScore models. Older accounts raise that average more than new ones do — newer tradelines instead offer benefits like utilization reduction and active account reporting.
If you’re unsure which type fits your situation, our credit boost strategy guide and eligibility guide are good starting points.
The Real Math Behind “Average Age of Accounts”
This is the one factor seasoned tradelines actually move, so it’s worth seeing the real calculation rather than taking it on faith:
Average account age = (sum of all account ages in months) ÷ (number of accounts)
Example: Someone with three accounts aged 12, 18, and 24 months has an average age of 18 months. Adding a new tradeline (0 months) drops that average to 13.5 months. Adding a seasoned tradeline at 96 months instead raises it to 37.5 months — a much larger shift, from the same single addition.
This is exactly why age matters more than most other single factors when the goal is specifically building credit history depth — but it’s also why a new tradeline isn’t “worse,” just aimed at a different part of your profile (utilization, active accounts) rather than this one.
What Are Seasoned Tradelines?
Seasoned tradelines are accounts open and in good standing for at least 24 months, often longer. Typical characteristics:
- 2+ years of age
- Consistent on-time payment history
- Low utilization (under 10%)
- Active, open status
These are commonly used ahead of home loans, business credit applications, or other situations where account history depth matters. The more seasoned the account, the more it typically shifts your average age — which is also why seasoned tradelines usually cost more than newer ones.
What Are New or Less-Seasoned Tradelines?
New tradelines under 24 months old can still be active and in good standing. Rather than moving average age significantly, they contribute differently:
- Improve revolving account count
- Reduce utilization, particularly on high-limit accounts
- Add reporting activity to a thin or dormant file
They’re a more affordable way to add an open, positive account, and they pair well alongside seasoned tradelines when stacking for broader impact rather than relying on one factor alone.
Seasoned vs. New — Quick Comparison
Seasoned Tradelines
- 2+ years of history
- Stable reporting activity
- Increases average account age
- Best for credibility and mortgage prep
New Tradelines
- Recently opened accounts
- Short or no payment history
- Useful for utilization reduction
- More affordable entry point
Want expert-curated bundles combining both? See our Tradeline Packages.
Which Type Should You Choose?
The right choice depends on which factor you’re actually trying to move: average account age, utilization, or report activity.
| Feature | Seasoned Tradeline | New Tradeline |
|---|---|---|
| Account Age | 24+ months | 6–24 months |
| Cost | Higher | More affordable |
| Best For | Account age, credibility | Utilization, activity, budget |
Still unsure? See buying AU tradelines safely or compare high vs. low limit tradelines for more angles on the decision.
For further independent reading on how tradelines are reported, see NerdWallet’s tradeline explainer.
Frequently Asked Questions
What is the difference between seasoned and new tradelines?
Seasoned tradelines have a long-standing credit history and consistent reporting activity, while new tradelines may have little to no payment history. See Seasoned AU Tradelines Explained for more detail.
Why do seasoned tradelines have more credit impact?
Seasoned tradelines carry aged credit history and tend to show stability, which mainly affects the average-age-of-accounts factor. See What Makes a Tradeline Seasoned.
Are new tradelines ever worth using?
Yes. They’re useful for quick bureau coverage or utilization reduction, and often work well alongside a seasoned line rather than in place of one. See High-Limit vs. Low-Limit Tradelines for related strategy.
How many tradelines should I add?
It depends on your goals and existing profile. See How Many Tradelines Should I Buy? for a fuller breakdown.
Can I buy seasoned tradelines in bundles?
Yes — bundled packages often mix seasoned and new lines to balance age, limit, and reporting goals. Browse Tradeline Packages for combinations.
Find the Right Tradeline for Your Goal
Compare seasoned and new AU tradelines by age, limit, and bureau — every listing is escrow-protected.