High-Limit vs. Low-Limit Tradelines: What Brokers Need to Know
Credit limit is one of the biggest factors in how a tradeline affects utilization — the ratio of credit used to credit available, which plays a real role in most credit scoring models. Higher-limit tradelines generally have more impact on utilization; lower-limit tradelines still add value for profile depth and account history.
Visit our homepage to explore tradeline strategies, or browse real-time inventory and pricing.
Watch: High-Limit vs. Low-Limit Tradelines

Reviewed by
Raquel Hudson, Tradeline Specialist
More than a decade of experience in tradeline placement, credit report analysis, and client support. Read her full background →
How Credit Limits Influence Your Credit Report
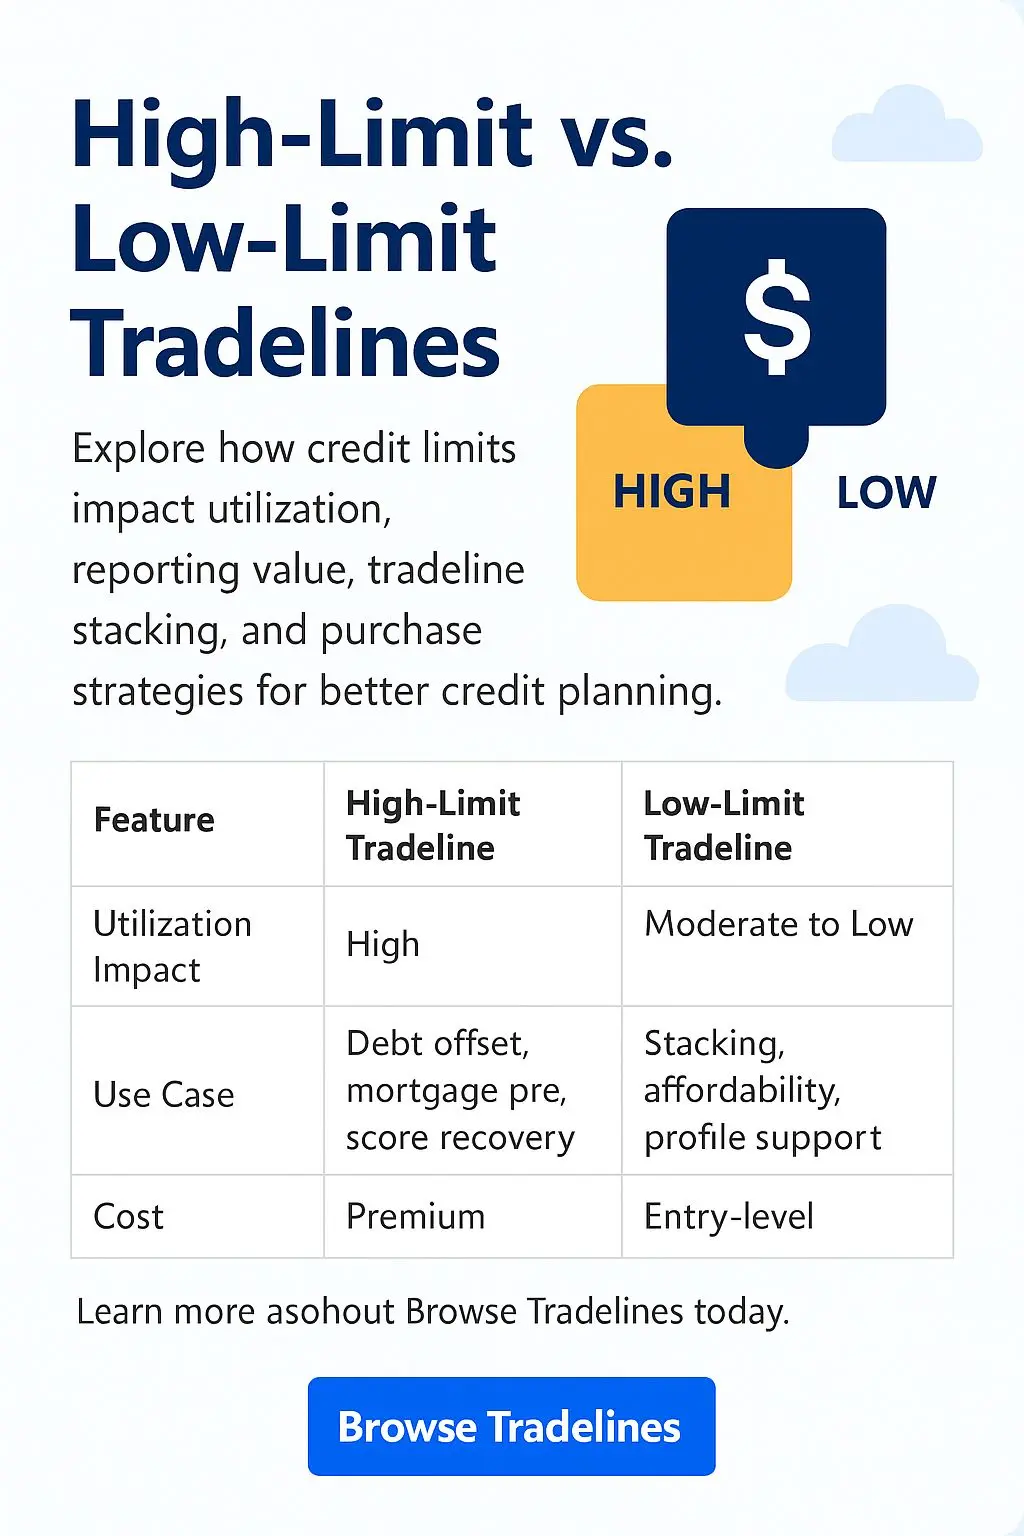
Credit limit is a major input into your credit utilization ratio — one of the more heavily weighted factors in most scoring models. Higher-limit tradelines tend to have a bigger effect on utilization; lower-limit tradelines still contribute to profile depth, account age, and revolving-credit diversity. Which matters more depends on where you are in your credit-building goals: reducing utilization ahead of a major application calls for a different approach than simply establishing a longer credit history.
Review our credit boost strategy guide to think through your own selection, or see our page on seasoned vs. new tradelines for how account age factors in alongside limit.
For background from an independent source, the CFPB’s overview of how credit scores are determined explains utilization’s role in more detail.
The Utilization Math, With a Real Example
Utilization is simply balance divided by limit, added up across your accounts. A concrete example shows why limit size has such an outsized effect:
- A $500 balance on a $2,000-limit card is 25% utilization
- The same $500 balance on a $15,000-limit card is roughly 3% utilization
Same balance, dramatically different impact — which is exactly why a higher-limit tradeline moves the utilization needle further, provided its own balance stays low.
Benefits of High-Limit Tradelines
High-limit AU tradelines generally have more influence on utilization, since a larger available limit changes the ratio more meaningfully than a small one. Common reasons brokers and buyers choose high-limit listings:
- Reducing an existing high utilization ratio
- Adding depth to a profile ahead of a mortgage or auto loan application
- Offsetting existing balances on other accounts
- Anchoring a broader tradeline-stacking strategy alongside lower-limit or seasoned lines
This reflects our current inventory mix too: across our verified listings, roughly 85% carry a $10,000+ limit, with the remaining 15% split between mid-range and lower-limit accounts — high-limit tradelines make up most of what’s actually available at any given time.
High-limit tradelines aren’t automatically the right fit for everyone, though. Someone rebuilding a profile after a period of inactivity may get more value from a mix that includes lower-limit, longer-history accounts instead. The right choice comes down to matching the tradeline to your specific goal — utilization reduction, profile depth, or a blend of both — rather than defaulting to the highest limit available.
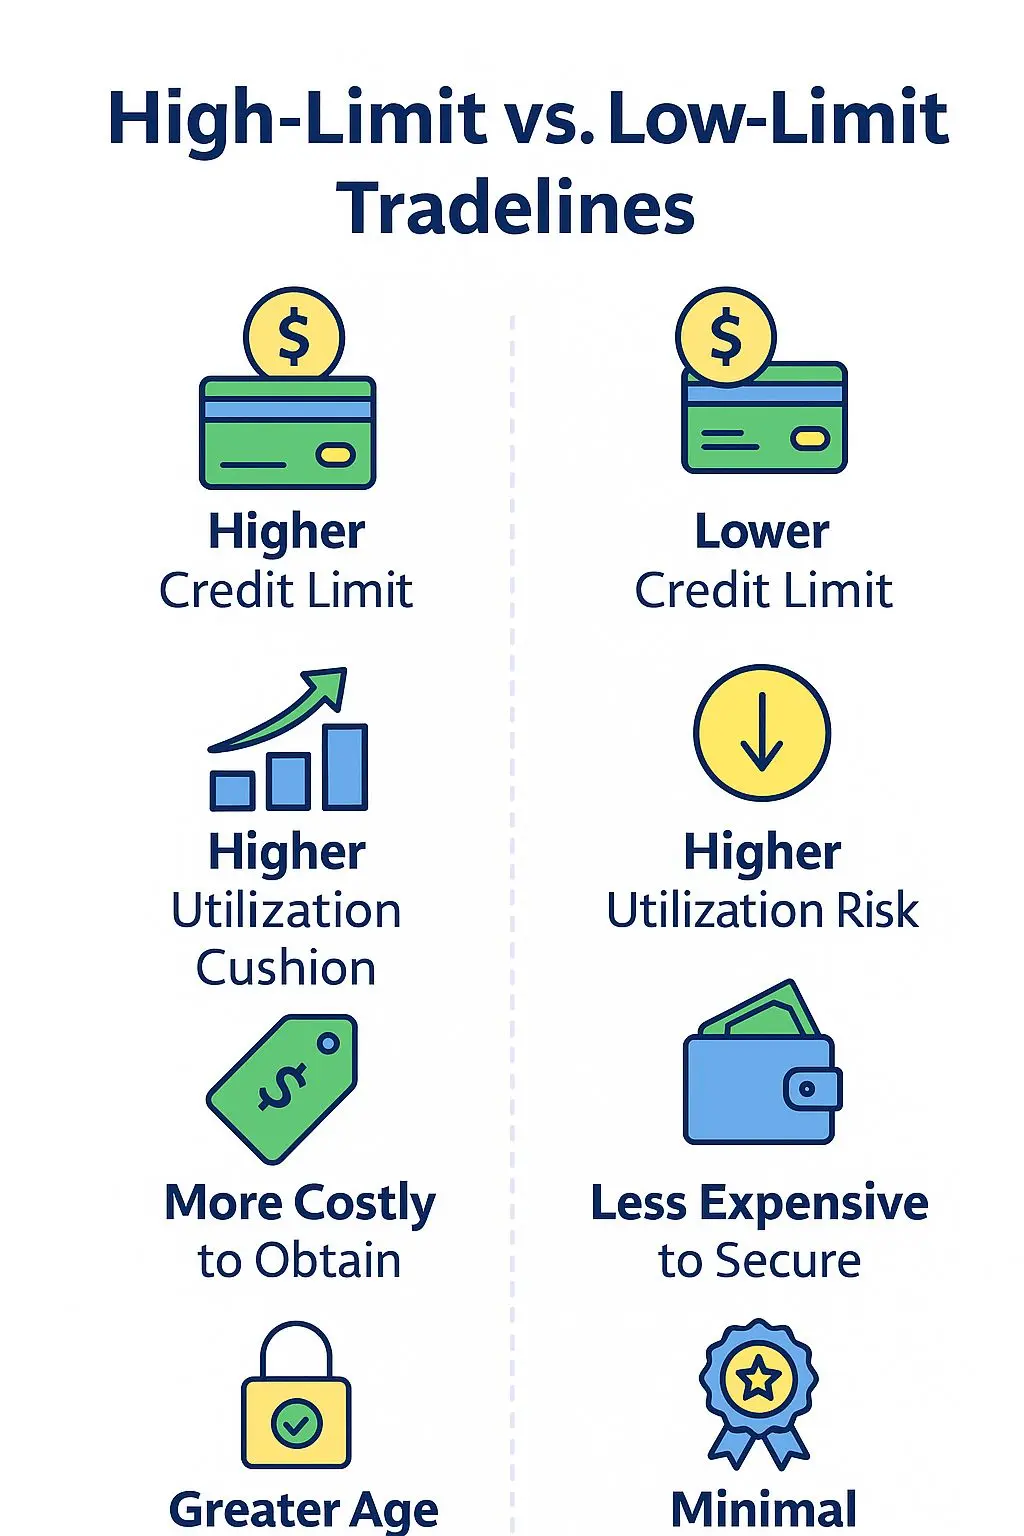
High-Limit vs. Low-Limit Tradelines, Side by Side
High-Limit Tradelines
- Available credit typically $10,000+
- Larger effect on utilization ratio
- Often used ahead of mortgage or major-loan applications
- Higher upfront cost
Low-Limit Tradelines
- Available credit typically under $5,000
- Smaller, but still real, utilization effect
- Useful for profile depth and affordability
- Lower cost of entry
When Low-Limit Tradelines Make Sense
Low-limit tradelines have less individual effect on utilization, but they’re still useful for adding positive revolving-account history and improving the appearance of consistent credit activity. They tend to work best for:
- Buyers building a first tradeline history on a thin credit file
- Rounding out a stacked profile alongside an existing higher-limit or seasoned account
- Budget-conscious purchases where affordability matters more than maximum utilization impact
Bigger isn’t automatically better — a low-limit account with strong age and clean history can be more useful for a specific profile than a higher-limit one that doesn’t fit the buyer’s actual goal.
Issuer Policies Matter as Much as the Limit Itself
The credit limit is only part of the story — the issuing bank’s own policies shape how much a tradeline can actually help:
- Some issuers report authorized users to all three bureaus; others report to only one or two
- Every account has a maximum number of authorized-user slots it can carry, independent of its limit
- A tradeline inherits the primary account’s entire payment history — a high limit paired with even one late payment can work against a buyer’s goals, not for them
This is why we screen listings for issuer reporting behavior and payment history together with limit, rather than treating limit as the only thing that matters.
Choosing the Right Credit Limit for Your Goals
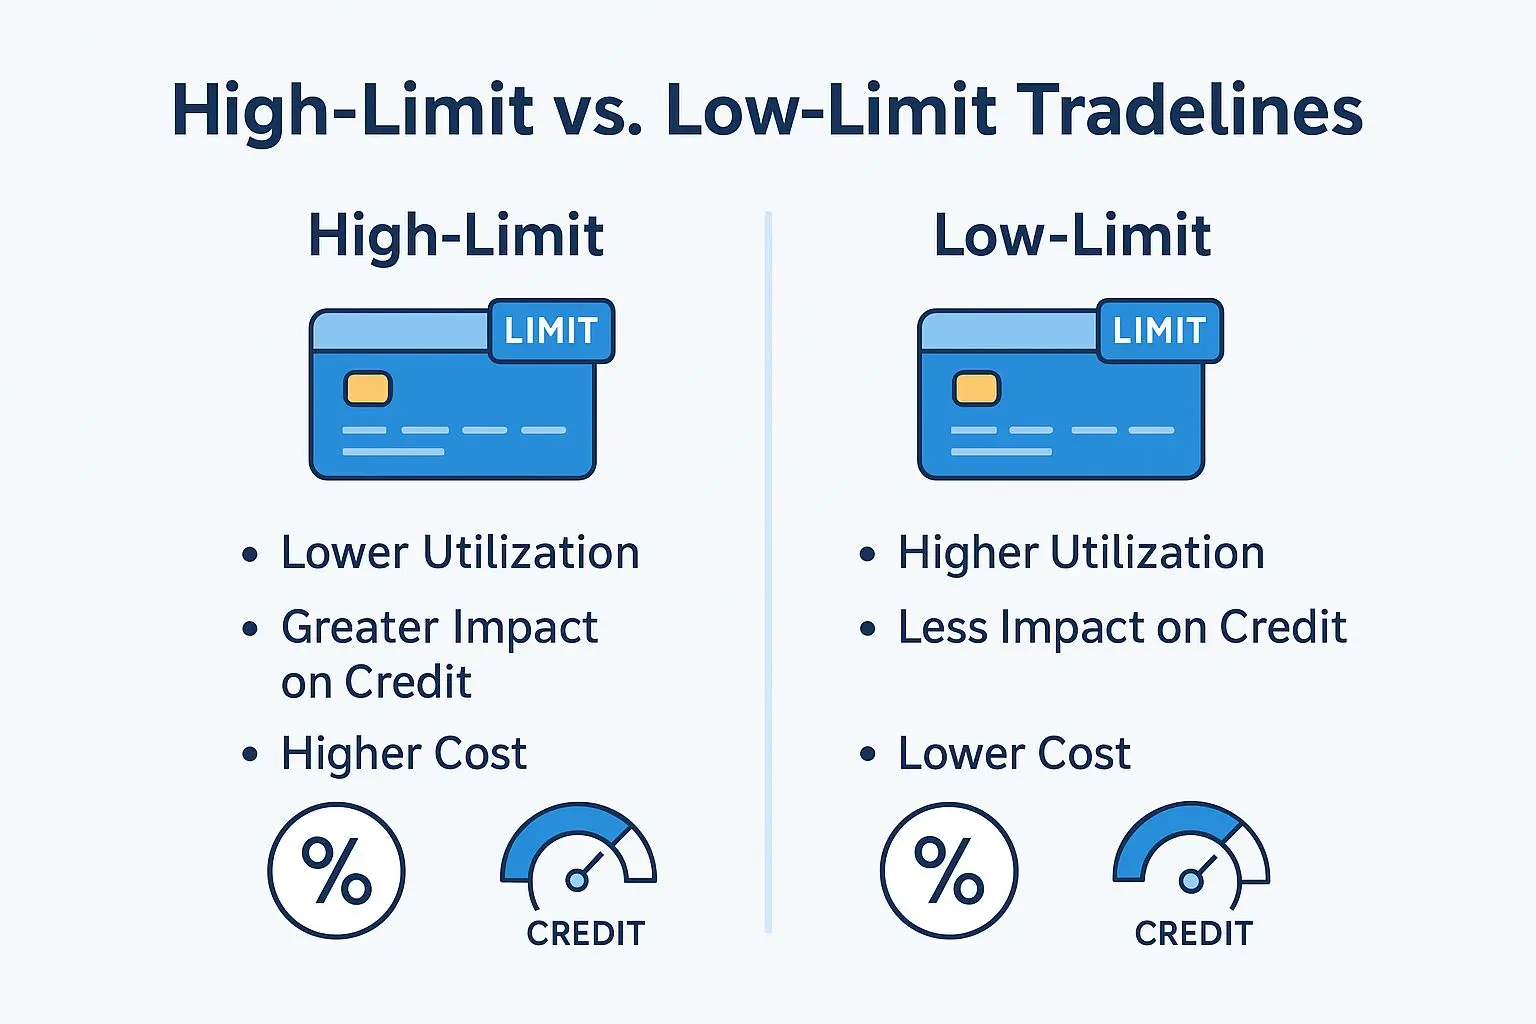
The right limit depends on your goals, budget, and current profile. This comparison covers the basics:
| Feature | High-Limit Tradeline | Low-Limit Tradeline |
|---|---|---|
| Utilization Impact | Larger | Smaller, but real |
| Common Use Case | Utilization reduction, major-application prep | Profile depth, affordability |
| Typical Cost | Higher | Lower |
Learn more about how long tradelines stay on your credit report to plan the timing of your purchase around key financial events.
According to Experian, keeping utilization below 30% is generally recommended for a healthy credit profile — a useful benchmark regardless of which limit tier you choose.
Frequently Asked Questions
What is the main difference between high-limit and low-limit tradelines?
High-limit tradelines typically carry available credit over $10,000, while low-limit tradelines are smaller. High-limit accounts generally have a larger effect on utilization and how a profile is perceived.
Do high-limit tradelines offer more benefit than low-limit ones?
For utilization specifically, usually yes — a larger limit has more room to lower the ratio. But “more benefit” depends on your actual goal; see our credit boost strategies guide for more context.
When should I choose a low-limit tradeline instead?
When affordability matters more than maximizing utilization impact, or when you’re adding to an already-strong profile rather than trying to move the needle on a single factor. See our custom tradeline combos page for how buyers typically mix the two.
Does credit limit affect how long a tradeline stays on my report?
No. Limit and reporting duration are unrelated. See how long tradelines stay on report for that timeline.
Are high-limit tradelines worth the higher cost?
It depends on your goal. If reducing utilization ahead of a major application is the priority, the larger effect often justifies the cost. If you’re mainly building profile depth, a lower-limit account may accomplish that at a lower price point.
About the Reviewer
Raquel Hudson, Tradeline Specialist
Raquel brings more than a decade of hands-on experience in the credit and tradeline industries, with deep knowledge of tradeline placement, credit report analysis, inventory management, and client support. She has reviewed hundreds of thousands of credit reports and helped clients better understand the factors that influence their credit profiles. Read her full background →
Find the Right Limit for Your Tradeline Strategy
Compare high and low-limit AU tradelines by limit, age, bureau, and reporting schedule. Every listing is escrow-protected and backed by our Posting Guarantee Policy.