The AU Tradeline Timeline: When They Post, Report, and Expire
A real look at how tradeline timing works — and why the exact number of days always depends on your specific card.
Return to the Buy Tradelines hub or explore credit bureau posting schedules.
Watch: How the Tradeline Timeline Works

Written by
Raquel Hudson, Tradeline Specialist
More than a decade of experience in tradeline placement, credit report analysis, and client support. Read her full background →
Why Timing Isn’t a Fixed Number
Card issuers don’t report account activity to credit bureaus in real time. Instead, they batch account data and submit it once per billing cycle, tied to the card’s statement closing date — not the date you were added as an authorized user. This is standard practice across the industry, not something unique to any one issuer.
That means the real timeline has two separate steps that both affect when a tradeline actually appears:
- Getting added before the statement closes. If you’re added after a card’s statement date, you’ll typically need to wait for the next full cycle — not the one that just closed.
- The issuer’s own reporting speed to each bureau. Once the statement closes, issuers vary in how quickly they transmit data to Experian, Equifax, and TransUnion — and not every issuer reports to all three.
Because both of these vary by issuer and by where a specific card sits in its billing cycle, any general number you see — including elsewhere on this site — is a reasonable estimate, not a fixed promise. Each individual listing on our marketplace shows its own expected posting window based on that specific account’s history.
Why Timing Matters for Brokers Specifically
Mistiming a purchase against a client’s deadline is one of the most common avoidable mistakes in this business. Buyers working toward a funding deadline need a tradeline that will realistically post and report before that date — not just eventually. Buyers building long-term history care more about consistency and duration than raw speed.
For background on how credit reports are structured generally, see Equifax’s credit education center.
The Real Stages, Start to Finish
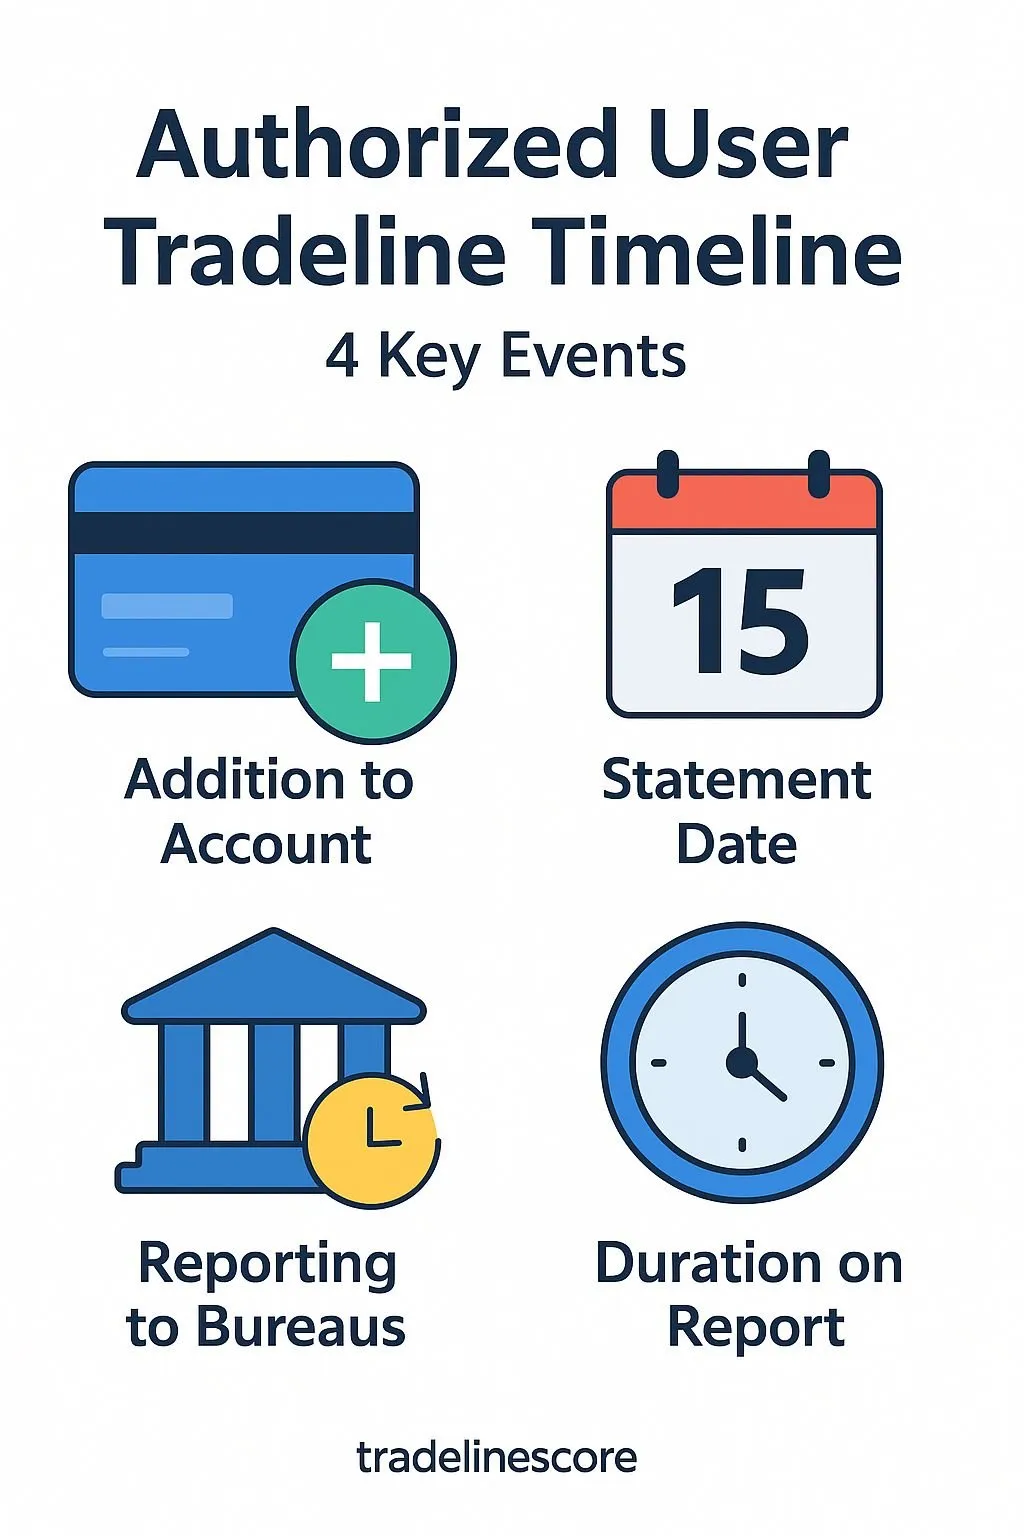
- Addition to the account. Once purchased, you’re added as an authorized user — typically within a few business days, though this depends on the cardholder completing the step on their end.
- Statement date alignment. The account only reports as of its next statement close, not the moment you’re added. Being added even one day after a close means waiting for the following cycle.
- Bureau reporting. After the statement closes, the issuer transmits data to the bureaus it reports to — timing varies by issuer.
- Duration on file. Once posted, most listings remain for a set window before the arrangement ends — each listing states its own expected duration.
Common Timing Mistakes to Avoid
- Assuming every tradeline follows the same schedule. Posting is controlled by each issuer’s own internal cycle, and it can differ by bureau even for the same card.
- Buying too close to a loan application or credit pull. Build in real buffer time after the expected statement date — rushing this step is one of the most common causes of a tradeline not appearing when it’s needed most.
See how tradeline posting works and compliance and escrow for related detail.
Recommended Resources
- How Many Tradelines Should I Buy? — bundle logic and use-case breakdowns
- Posting Guarantee Policy — what happens if a listing doesn’t post as expected
Frequently Asked Questions
Why do different sources give different timing estimates?
Because posting speed genuinely varies by issuer and by where a specific card sits in its billing cycle. A general estimate is only ever an average — the exact number for any one listing depends on that account’s real statement date and reporting history, which is why each listing shows its own expected window rather than a single site-wide number.
What happens if I’m added right after a card’s statement closes?
You’ll typically need to wait for the following billing cycle, since the account only reports as of its next statement close — not the date you were actually added.
Do all three credit bureaus report at the same time?
No. Not every issuer reports to all three bureaus, and even when they do, timing can differ by bureau. Each listing notes which bureaus it has historically reported to.
How long does a tradeline typically stay on my report?
This varies by the specific arrangement — each listing states its own expected duration rather than a single fixed number that applies to every account.
What if a tradeline doesn’t post within the expected window?
See our Posting Guarantee Policy for what happens and what options are available if a listing doesn’t post as expected.
Match Timing to Your Actual Goal
Every listing shows its own expected posting window, based on that specific account’s real history — not a generic estimate.